

Self - Credit Builder & Cards
by Self Financial, Inc.
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
Building credit can feel frustrating when the usual route starts with a credit check, a deposit, or a rejection that gives you no practical next step. I approached Self - Credit Builder & Cards as a tool for that specific problem rather than as a general banking replacement. It is a free finance app from Self Financial, Inc., designed to help people work toward stronger credit habits and a possible credit card path. My overall impression is that it makes sense when your priority is establishing a track record gradually, but it requires patience and careful attention to the account terms shown during setup.
The app has become a widely used option, with an average rating of 4.7 from around 102 thousand ratings and more than a million installs. That level of adoption is useful context, but it is not a reason to treat the app as automatically right for everyone. Credit-building products affect real money and personal information, so I would judge this one by how clearly it explains each step, how much control it gives me before committing, and whether its slower approach matches my situation.
How the credit-building approach feels in everyday use
The central idea is different from opening a conventional rewards card and spending immediately. Instead, the app is aimed at people who want to create a payment history while working toward access to a credit card. The store summary emphasizes that no credit check is required, which makes the starting point less intimidating for someone with limited or damaged credit history. I found that the most important mindset shift is to see it as a structured credit routine, not as extra spending power.
A realistic example would be someone who has just moved to the country, has never used credit, or is recovering from missed payments. They might use the app to set aside a manageable amount on a regular schedule, keep the account in good standing, and monitor the process rather than applying for several cards at once. That can be more comfortable than repeatedly submitting applications and collecting hard inquiries, although the user still needs to read the exact agreement and understand what obligations come with the selected product.
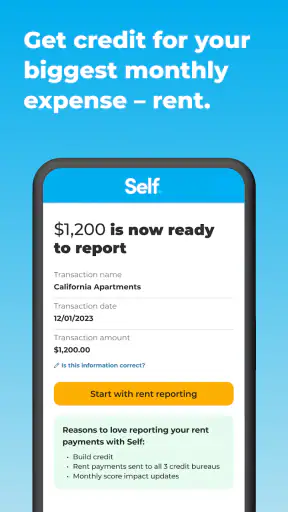
I would not choose it for a person who needs a large available balance today, wants travel rewards, or expects an instant improvement in a credit score. The product is built around gradual progress. Credit reporting is not a magic reset button, and responsible behavior outside the app still matters. Rent, utilities, existing loans, and other accounts may remain important parts of a person’s broader financial picture.
What I would check before creating an account
The first useful habit is to slow down during onboarding. I would read every screen that explains payment amounts, timing, account obligations, card eligibility, and any option that changes the product being considered. A no-credit-check entry point can be appealing, but it should not encourage anyone to skip the contract details. If a monthly commitment would make your budget tight, the right decision may be to wait rather than sign up simply because approval feels easier.
I would also prepare the information needed for identity and account setup before starting. Finance apps commonly ask for sensitive details because they must connect a real person to a financial account. That does not make the request suspicious by itself, but it does make the moment important. I prefer entering information only after checking that I am using the official app and that the developer shown in the store is Self Financial, Inc.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
One practical tip is to take time to compare the displayed payment schedule with your actual payday. A credit-building plan is easier to maintain when its due dates fit your cash flow. Even a product intended to help credit can become stressful if the payment lands just before rent or another essential bill. I would treat the scheduled amount as a fixed budget item, not as a casual subscription that can be forgotten.
Controls that matter more than the headline promise
The useful controls are the ones that let me understand and manage an obligation before it becomes a problem. I would look for the payment amount, the next due date, the current account status, and any clearly presented route for changing or ending a product. I would also review notifications and account messages instead of dismissing them, because a credit-related account is not something I would manage purely from memory.
The app’s current version is 9.0.0, and it supports devices running Android 7.0 or later. That broad compatibility is helpful if you use an older Android phone, but I would still keep the operating system updated where possible. A finance app should be used on a device with a screen lock and current security updates, especially if the phone is shared or regularly connected to public networks.
I would make a simple personal record of the agreement at the moment I enroll: the product name, scheduled payment, due date, and any conditions attached to card access. This is not about distrusting the app; it is about making the account understandable outside the app as well. If a notification is missed or the interface changes after an update, having my own record makes it easier to spot a mistake quickly.
Another non-obvious trade-off is that convenience can hide commitment. A polished mobile screen may make a financial product feel as easy as downloading a budgeting tool, but the consequences are different. I would never tap through an offer while distracted, and I would avoid enrolling while under pressure to repair my credit immediately. The strongest control is still choosing a payment that I can reliably maintain.
Trust, privacy, and sensitive moments
Trust here should be judged through visible choices rather than assumptions. When an app handles identity, payment, and credit-related information, I want to see why each piece of information is requested, which account it applies to, and what action I am authorizing. I would read the privacy and permission prompts in context, especially when the app asks for access that is not obviously necessary for the screen I am using.
I would also pay attention to the difference between an informational screen and a confirmation screen. Before submitting an application, authorizing a payment, or accepting a new account condition, I would look for the final amount and timing. If the wording is unclear, I would stop and seek clarification through the app’s official support route instead of guessing. That habit is more valuable than relying on a star rating.
Data-sensitive moments include identity verification, linking a payment method, reviewing account activity, and opening anything related to a card. I would avoid completing these steps over an unsecured public connection and would not share login codes with another person. If I receive an unexpected message asking for credentials, I would open the app directly rather than following the message.
I also think it is important to separate the app’s role from the user’s broader financial identity. A credit-building account may be useful, but it should not become the only place where someone checks their finances. I would compare the activity shown inside the app with my bank records and keep an eye on withdrawals. That extra check can catch a forgotten schedule, a duplicate expectation, or a misunderstanding before it affects the rest of the month.
Who gets the most value from it
I see the strongest fit for someone with little credit history, someone rebuilding after financial difficulty, or someone who wants a more deliberate first step than applying for several traditional cards. The no-credit-check positioning can remove one common barrier at the start. It may also suit a person who values a guided routine and is willing to make regular payments without expecting immediate rewards.
The app can be especially useful when the user has a clear purpose. For example, a person planning to rent a new apartment might want to begin improving their credit profile well before an application, rather than waiting until the last minute. In that situation, the app is best treated as one part of a longer plan: keep payments on time, reduce unnecessary debt, review reports when appropriate, and avoid taking on more accounts than the budget can support.
It is less suitable for someone who already has excellent credit and mainly wants cashback, travel points, or a generous introductory offer. A conventional card may be more valuable for that user if they can pay the balance in full and qualify for favorable terms. It is also not a good fit for anyone who cannot reliably meet a recurring payment. No credit-building strategy is worth creating a new strain on essential expenses.
People who prefer face-to-face help may also find a mobile-first experience limiting. I like being able to review an account from my phone, but not everyone wants to resolve financial questions through an app. If you need extensive branch support or a personal adviser for every decision, a local bank or credit union may feel more comfortable, even if the application process is slower.
How it compares with familiar alternatives
The usual alternatives fall into several groups. A secured credit card may offer a more familiar card experience, but it often requires an upfront deposit and may involve an application process that feels less accessible. An ordinary starter card can provide spending flexibility and possibly rewards, yet it may be difficult to obtain with no history or a damaged score. A credit union may offer personal guidance and local service, while a budgeting app can help organize money without directly serving as a credit-building product.
What distinguishes Self is the emphasis on building credit first and working toward a card rather than leading with everyday purchases. That focus can be an advantage for a beginner who needs structure. The trade-off is that it may feel less immediately useful than a card you can use for groceries or transport. I would choose between these options based on the goal, not on the most attractive advertisement: establish history, access spending power, receive guidance, or simply control a budget.
A useful comparison workflow is to write down the total commitment, the payment schedule, the card conditions, and the consequences of missing a payment for every option under consideration. Then compare those details with your monthly budget. Looking only at “no credit check” or “free app” is too narrow. The real question is whether the product remains manageable after the first month, when the novelty has disappeared.
Small routines that make the app safer to use
I would turn on only the notifications that help me act on time, then review them rather than swiping them away. A calendar reminder placed several days before the due date gives me room to correct a bank balance or payment method. I would also open the account after each scheduled payment to confirm that the status matches what I expected, especially during the first few cycles.
I would keep the app protected with the strongest sign-in option available on my device and avoid storing login details where another person can access them. If I replace my phone, I would sign out of the old device and verify the new session carefully. These steps are simple, but they matter more for a finance app than for a casual shopping or entertainment app.
Another useful workflow is to review the account before making a separate credit application. If the goal is to build history, applying for several products at once can work against a cautious plan. I would first decide whether I actually need another account, check my budget, and consider how the new obligation fits with the existing schedule. The app should support a measured strategy, not encourage a race toward more credit.
I would also avoid treating a future card path as guaranteed spending capacity. If the app presents an opportunity to work toward a card, I would study the eligibility language and terms at that point instead of planning a purchase around it. That distinction protects the user from making a financial decision based on an expectation rather than an available account.
Where the experience may create friction
The biggest limitation is the pace. Someone hoping to see a quick score change may become disappointed, because responsible credit building depends on time and consistency. The app can organize the process, but it cannot make every lender view a person identically or replace broader financial repair. I would recommend it only to someone prepared to measure progress over a longer horizon.
There is also the mental burden of another account to monitor. Even a manageable payment becomes a problem when the user has several subscriptions, loans, and cards competing for attention. The app is not a substitute for a complete budget. I would include its scheduled payment in the same calendar or money-management system used for rent, utilities, and other obligations.
The card-related path may also require careful reading because “working toward” a card is not the same as having a traditional card immediately. I would not assume that using the credit-building side automatically provides every feature associated with a standard credit card. Anyone mainly interested in purchases, rewards, or a high spending limit should compare a conventional card directly rather than choosing this app for the wrong reason.
Finally, the app’s convenience does not remove the need to contact support when an account detail looks wrong. A delayed payment, unfamiliar transaction, or confusing status deserves prompt attention. I would save confirmation messages and note the date of any support interaction. That creates a clear trail and reduces the chance of relying on memory during a financial dispute.
My cautious recommendation
After reviewing the experience, I would recommend Self - Credit Builder & Cards to a specific kind of user: someone who wants a structured route into credit, does not want a credit check at the starting point, and can commit to regular payments without stretching the household budget. Its free download and Everyone age rating make it approachable, but approachability should not be confused with zero responsibility.
For me, the deciding test is simple: can I explain the payment, the timing, the account purpose, and the exit or support process before I enroll? If yes, the app can be a practical part of a patient credit plan. If not, I would pause and compare it with a secured card, a credit union, or a budgeting tool that better matches the immediate need.
Self Financial, Inc. has built an app with a clear audience and a focused use case. I like that it starts from the credit-building problem instead of pretending every user needs another shopping card. Still, I would use it deliberately, check sensitive account actions closely, and keep independent records of payments. My recommendation is positive but conditional: choose it for steady credit-building structure, not for instant results or effortless borrowing.
Pros
- Helps establish payment history with regular, manageable credit-building payments.
- Reports eligible activity to major credit bureaus, depending on the selected product.
- Offers access to secured and credit-building card options in one app.
- Provides budgeting tools and account tracking for better financial organization.
- Application and account management can be completed conveniently from a phone.
Cons
- Some features may require monthly fees or other account charges.
- Credit-building results are not immediate and depend on consistent payments.
- Approval, limits, and product availability can vary by state and applicant.
- Late or missed payments may hurt your credit instead of improving it.
- Customer support and account issues may take time to resolve through the app.
FAQs for Self - Credit Builder & Cards
What is Self – Credit Builder & Cards, and how does it work?
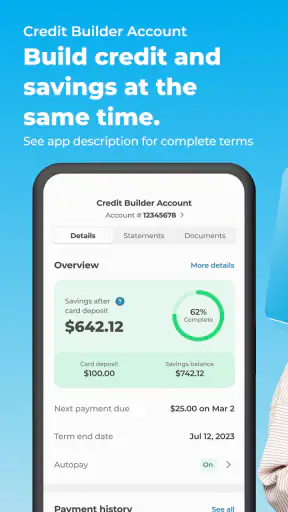
Self is a financial app designed to help users build or establish credit through a Credit Builder Account. Instead of receiving the borrowed money immediately, you generally make scheduled monthly payments into an account, and those payments may be reported to major credit bureaus. When the account term ends, the saved funds may become available to you, minus applicable fees and interest.
Can Self really improve my credit score?
Self may help strengthen your credit history when your payments are reported to participating credit bureaus and you consistently pay on time. However, results are not guaranteed, and your score can also be affected by existing debts, missed payments, credit utilization, account age, and other information in your credit reports. The app is a credit-building tool, not a promise of a specific score increase.
What fees and costs should I expect before signing up?
Before opening an account, carefully review the plan details because Self products can include an administrative fee, interest charges, monthly payments, and possible costs associated with optional features or cards. The total amount you pay may be higher than the amount ultimately released to you. Pricing, eligibility, and available plans can vary, so read the agreement rather than relying only on promotional estimates.
Does Self provide a credit card, and is it secured?
Self may offer a secured credit card to eligible customers who meet the company’s requirements, often after making progress with a Credit Builder Account. A security deposit or available balance may determine the spending limit, depending on the product terms. Card approval is not automatic, and users should check the current agreement for annual fees, interest rates, reporting practices, and upgrade conditions.
Is Self safe to use, and what information is required?
Self uses account verification and personal financial information to assess eligibility, manage payments, and provide its credit-building services. As with any financial app, download it only from the official Google Play Store or Apple App Store and review privacy permissions before registering. Enable strong account security, monitor bank transactions and credit reports, and contact official support if you notice suspicious activity or unexpected charges.

Self - Credit Builder & Cards
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@self.inc, visit https://www.self.inc, or review their https://www.self.inc/privacy-policy.










